Which Lenders Count Suite Rent When You Buy a Triplex or Fourplex Home in BC? (2026)
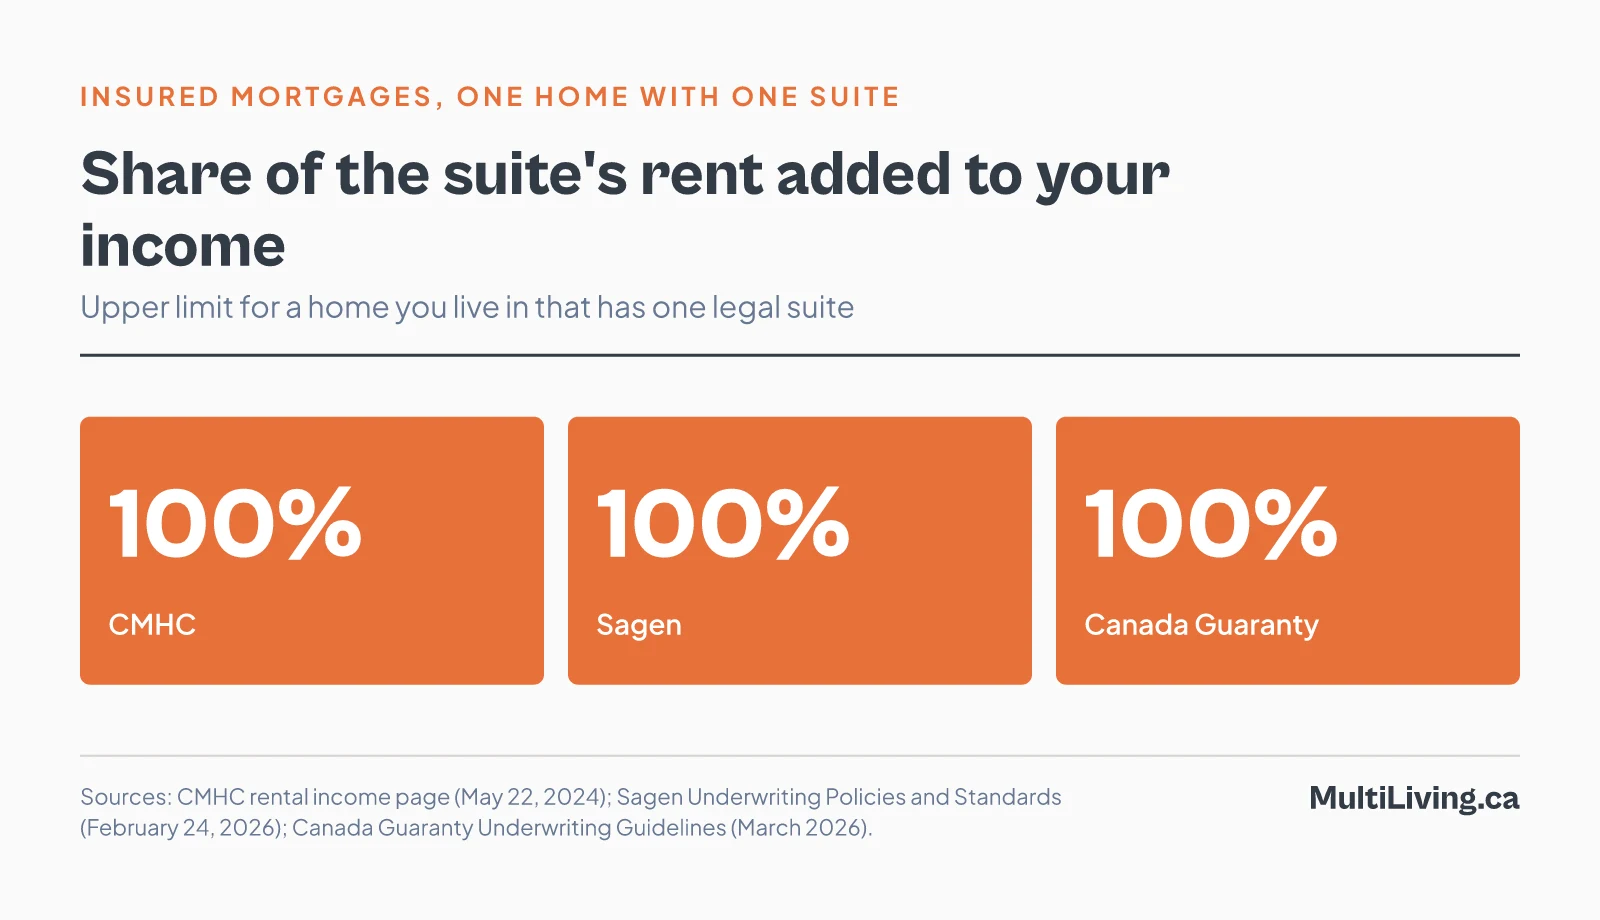
CMHC, Sagen and Canada Guaranty let a lender add up to 100% of a legal suite's rent to your income. Above $1.5 million, each lender sets its own rule.
By MultiLiving Editorial · November 11, 2026
Questions about this guide: Gary Paul, REALTOR®, Personal Real Estate Corporation, Grand Central Realty, 778-828-7476
If you buy one home in a triplex or fourplex, live in it, and the home has one legal suite, a lender giving you an insured mortgage can add up to 100 percent of the suite's rent to your income. The three companies that insure mortgages in Canada set that limit: CMHC, Sagen and Canada Guaranty. Your lender may count less, so ask. An insured mortgage needs a price below $1.5 million. Above that, each lender sets its own rule. Coast Capital Savings publishes its rule in a guide for mortgage brokers.
What the three insurers allow
With a down payment under 20 percent, you typically need mortgage insurance, according to the Financial Consumer Agency of Canada. For a home you live in with one suite:
- CMHC allows up to 100 percent of the gross rent, which is the rent before any costs. Property tax and heat for the home may be left out of your costs.
- Sagen accepts 100 percent of the rent and leaves tax and heat out. The rent is shown by a signed lease, or by the market rent stated by an appraiser (the person the lender hires to value the home).
- Canada Guaranty allows up to 100 percent, and tax and heat may be left out. It uses the lower of the lease rent and the appraiser's market rent.
With the appraiser's figure, Sagen and Canada Guaranty expect the lender to allow for months the suite sits empty.
Why your home counts as two units
The insurers set these rules by the number of units in the home you buy. CMHC's page for owners who add a suite counts the home as one unit and each suite as another. By that count, a strata home with one suite is two units. No insurer page says this in those words, so ask your lender to confirm it in writing.
Two suites make three units, and all three insurers drop to 50 percent of the rent. The same 50 percent applies to a family that buys every home in the building as one property.
Sagen and Canada Guaranty review an unauthorized suite case by case.
A worked example
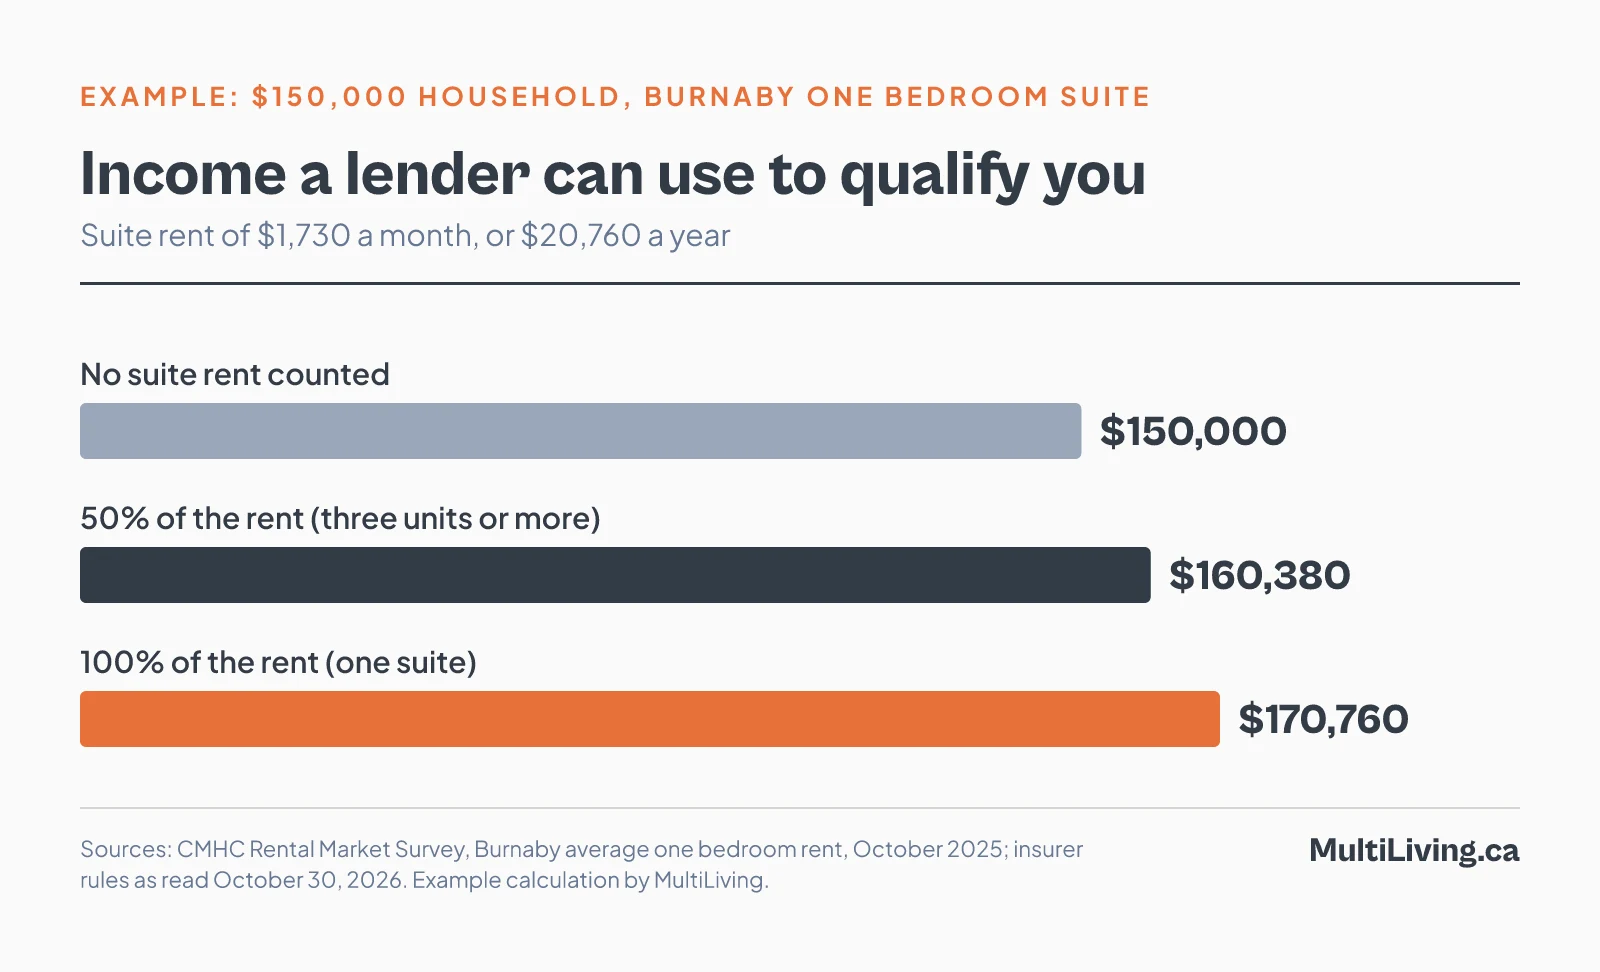
Say your household earns $150,000 a year, and your home in a Burnaby fourplex has a one bedroom suite. CMHC's October 2025 Rental Market Survey put the average rent for a one bedroom apartment in Burnaby at $1,730 a month. That survey counts rental apartment buildings, so the appraiser's figure for your suite may differ.
A year of rent is $1,730 times 12, or $20,760. Counted in full, it raises your qualifying income to $170,760. At 50 percent, the share for three units or more, it would be $160,380.
CMHC lets your housing costs reach 39 percent of your income. With no suite, that is $4,875 a month on $150,000. With the suite counted in full, 39 percent of $170,760 a year is $5,549.70 a month, or $674.70 more each month for your mortgage payment. The lender tests that payment at a higher rate than you will pay, as our stress test guide explains.
Above $1.5 million, the lender decides
CMHC insures a home only when the price is below $1,500,000. At $1.5 million or more, the minimum down payment is 20 percent, and the rent rule is the lender's own.
On October 28, 2026, 9 homes for sale in Vancouver and Burnaby triplexes and fourplexes had "Legal Suite" in their MLS® record. Only 3 were priced below $1.5 million, all in one Collingwood project listed by Macdonald Realty, and only one of those describes a suite in its listing text. The other 6 ask $1,668,000 to $2,633,000.
Coast Capital Savings publishes its rules in a guide for mortgage brokers. The lender says that on an uninsured mortgage for a home you live in, it adds back 100 percent of the suite's rent, for up to 2 suites, and each suite needs a kitchen with a fridge and stove, a bathroom and a private entrance. Other lenders set their own rules, so ask each one for its rule in writing.
The federal changes of 2024
Since December 15, 2024, the insured price limit is $1.5 million and new homes can get a 30-year insured mortgage, according to the Department of Finance Canada. CMHC's suite program is for people who already own a home.
What to ask a broker
In our view, a mortgage broker is the right person to put these questions to several lenders:
- Will you count 100 percent of the suite's rent, in writing?
- Do you treat my strata home and its suite as two units?
- Will you use the lease, the appraiser's market rent, or the lower of the two?
Questions buyers ask
Does a lock-off suite count?
Ask your lender. The test at Coast Capital Savings is a kitchen, a bathroom and a private entrance. See our lock-off suite guide.
Does the suite need a tenant before I buy?
Sagen and Canada Guaranty accept the appraiser's market rent in place of a lease, so an empty suite in a new home can still count.
Where can I find homes with a suite?
Our counts of Vancouver half duplexes and Burnaby homes for two generations list them by price.
Next step
To see which homes fit your budget with the suite's rent counted, talk to our team.
General information only. The income and rent figures here are examples based on rules in force on October 30, 2026, and are not financial or mortgage advice. Speak to a licensed mortgage broker before you make an offer.
Sources
- CMHC, "Rental income", published May 22, 2024, read October 30, 2026.
- CMHC, "Purchase" (homeowner mortgage loan insurance), no date shown, read October 30, 2026.
- CMHC, "CMHC Refinance", no date shown, read October 30, 2026.
- Sagen, Underwriting Policies and Standards, "Covenant Underwriting", modified February 24, 2026, read October 30, 2026.
- Canada Guaranty, Underwriting Guidelines, section 3.3.4, March 2026 edition, read October 30, 2026.
- CMHC, Rental Market Survey data tables, Vancouver 2025, Table 1.1.2, October 2025 survey, read October 30, 2026.
- Coast Capital Savings, "Rental Income Guidelines", file dated June 19, 2024, read October 30, 2026.
- Financial Consumer Agency of Canada, "How much you need for a down payment", page dated October 15, 2025, read October 30, 2026.
- Department of Finance Canada, "Boldest mortgage reforms in decades come into force today", December 15, 2024, read October 30, 2026.
- MultiLiving count of Active MLS® listings in Vancouver and Burnaby whose building holds three or four homes and whose suite field reads "Legal Suite", counted October 30, 2026, 11:41 PM PT, from listings last updated October 28, 2026, 10:33 PM PT. Our copy of the MLS® listings holds homes built in 2025 or later.