Which Website Has a Calculator for the Duplex Price I Can Afford in Greater Vancouver? (2026)
Our calculator at /affordability finds your top price by CMHC's rules. How to use it, two worked examples, and the Vancouver and Burnaby half duplexes that fit.
By MultiLiving Editorial · November 19, 2026
Questions about this guide: Gary Paul, REALTOR®, Personal Real Estate Corporation, Grand Central Realty, 778-828-7476
MultiLiving's affordability calculator shows the highest price a lender's test allows for your income, debts, down payment and rate. It uses CMHC's limits: housing costs up to 39 percent of income and all debts up to 44 percent, tested at your rate plus 2 points, or 5.25 percent if higher. It adds CMHC's premium below 20 percent down, and assumes $150 a month for heat, a $350 strata fee with half counted, and property tax of 0.3 percent of the price a year. The other tool is a pre-approval from a lender or mortgage broker. The Financial Consumer Agency of Canada's Mortgage Qualifier Tool tests one price you type in. Its page, last changed March 1, 2019, still says 20 percent down starts above $1 million. It now starts at $1.5 million.
How to use our calculator
- Annual income: your household's yearly income before tax.
- Monthly debts: car, card and credit line payments. The page opens at $500, so set your own figure.
- Down payment: the cash you will put down, after closing costs.
- Interest rate: your lender's quote. Without one, use the Bank of Canada's August 2026 average for new mortgages fixed 5 years or more: 4.12 percent with insurance, 4.58 percent without.
- First-time home buyer and Newly built home: change the transfer tax line only. The new home box is ticked when the page opens.
- 25 or 30 years: CMHC Home Start insures 30 years when one of you is a first-time buyer or the home is newly built. With 20 percent down or more, ask your lender how many years it allows.
"Monthly Payment at Your Rate" is the payment at the rate you entered, and "Mortgage, With Insurance" includes the CMHC premium.
Two worked examples
We ran the calculator's code with no other debts.
Earning $180,000, with $120,000 to put down, at 4.1 percent:
- 25 years: a top price of $915,400.
- 30 years: $970,700. The loan is $850,700, plus a CMHC premium of $28,073 (3.30 percent). The page shows a payment of $4,229 a month at 4.1 percent, with interest compounded twice a year, the way Canadian lenders state rates. The loan passed the test at 6.1 percent.
Earning $250,000, with $300,000 to put down, at 4.6 percent:
- 25 years: $1,402,100.
- 30 years: $1,474,300. With 20.3 percent down, there is no premium. Banks use the same test rate under OSFI's rule. The payment is $5,990 a month.
What each input changes
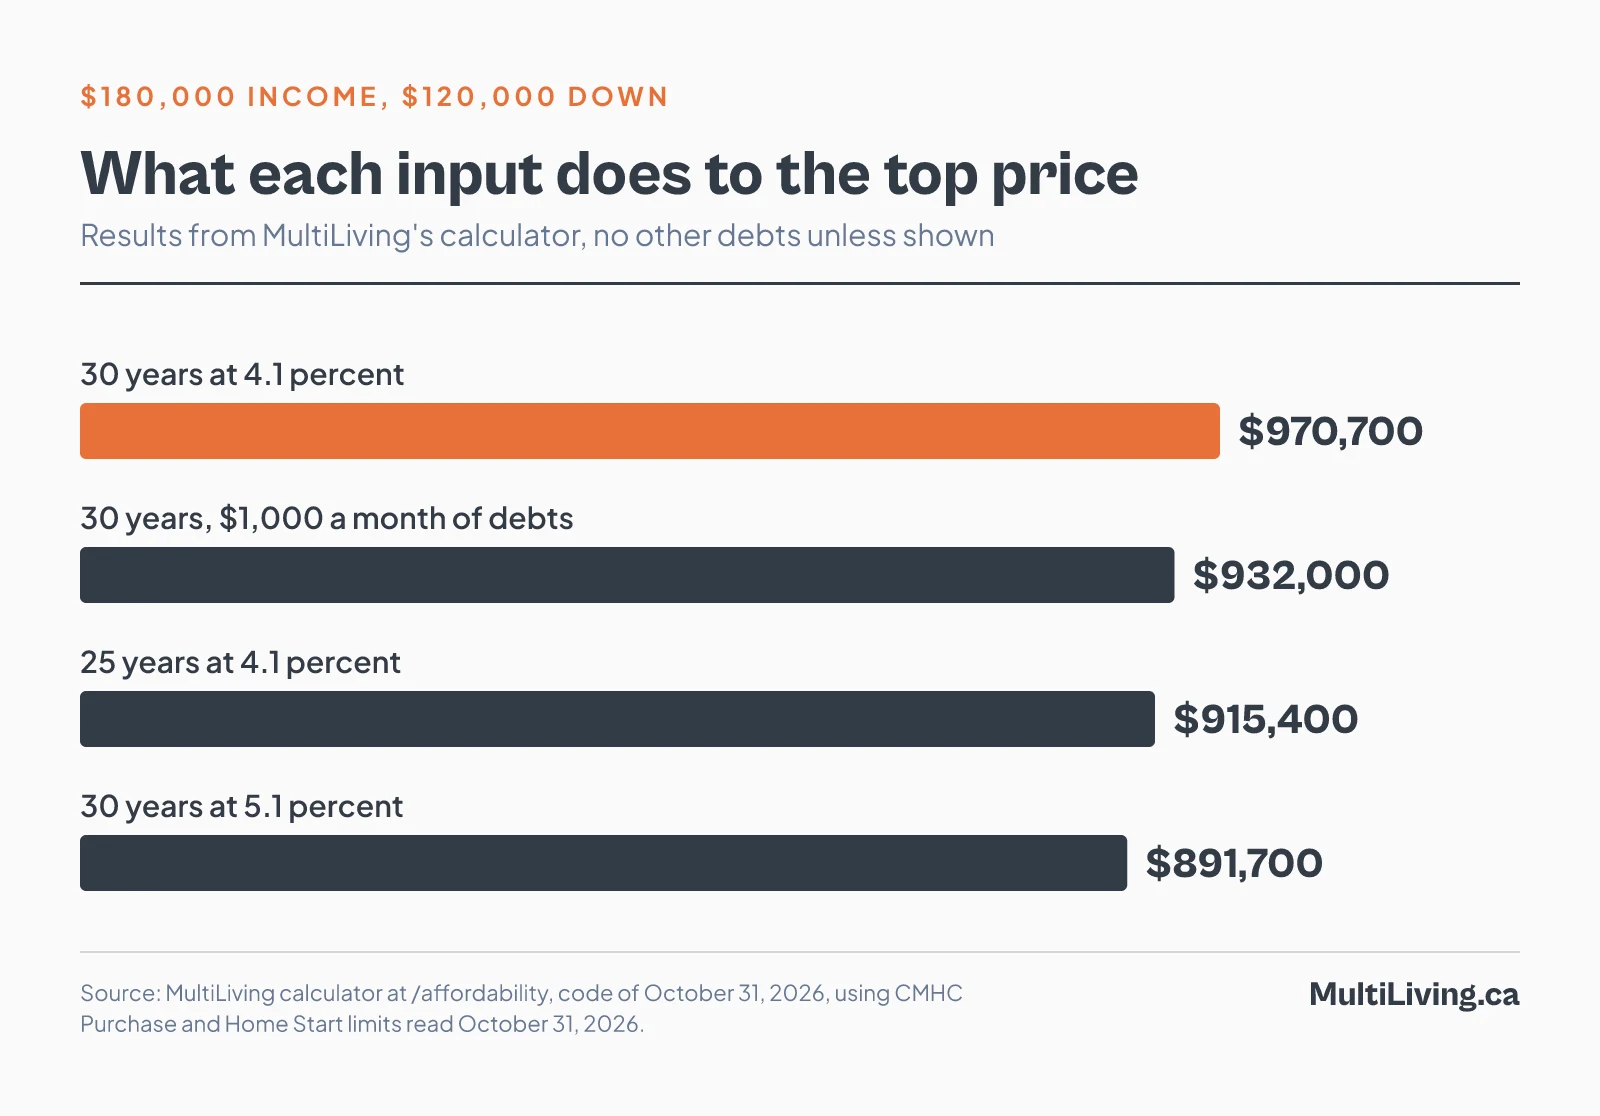
For the first household on 30 years, which gives $55,300 more than 25:
- At 5.1 percent, the top price falls from $970,700 to $891,700, or $79,000 less.
- Other debts of $500 a month change nothing. Housing can take 39 percent of income and all debts 44 percent, so other debts lower the price only past 5 percent of income: $750 a month here. At $1,000 a month the top price is $932,000.
In our view, run it again at one point above your quote. That shows the price that still passes the test if rates rise before you buy.
Half duplexes at or below each price
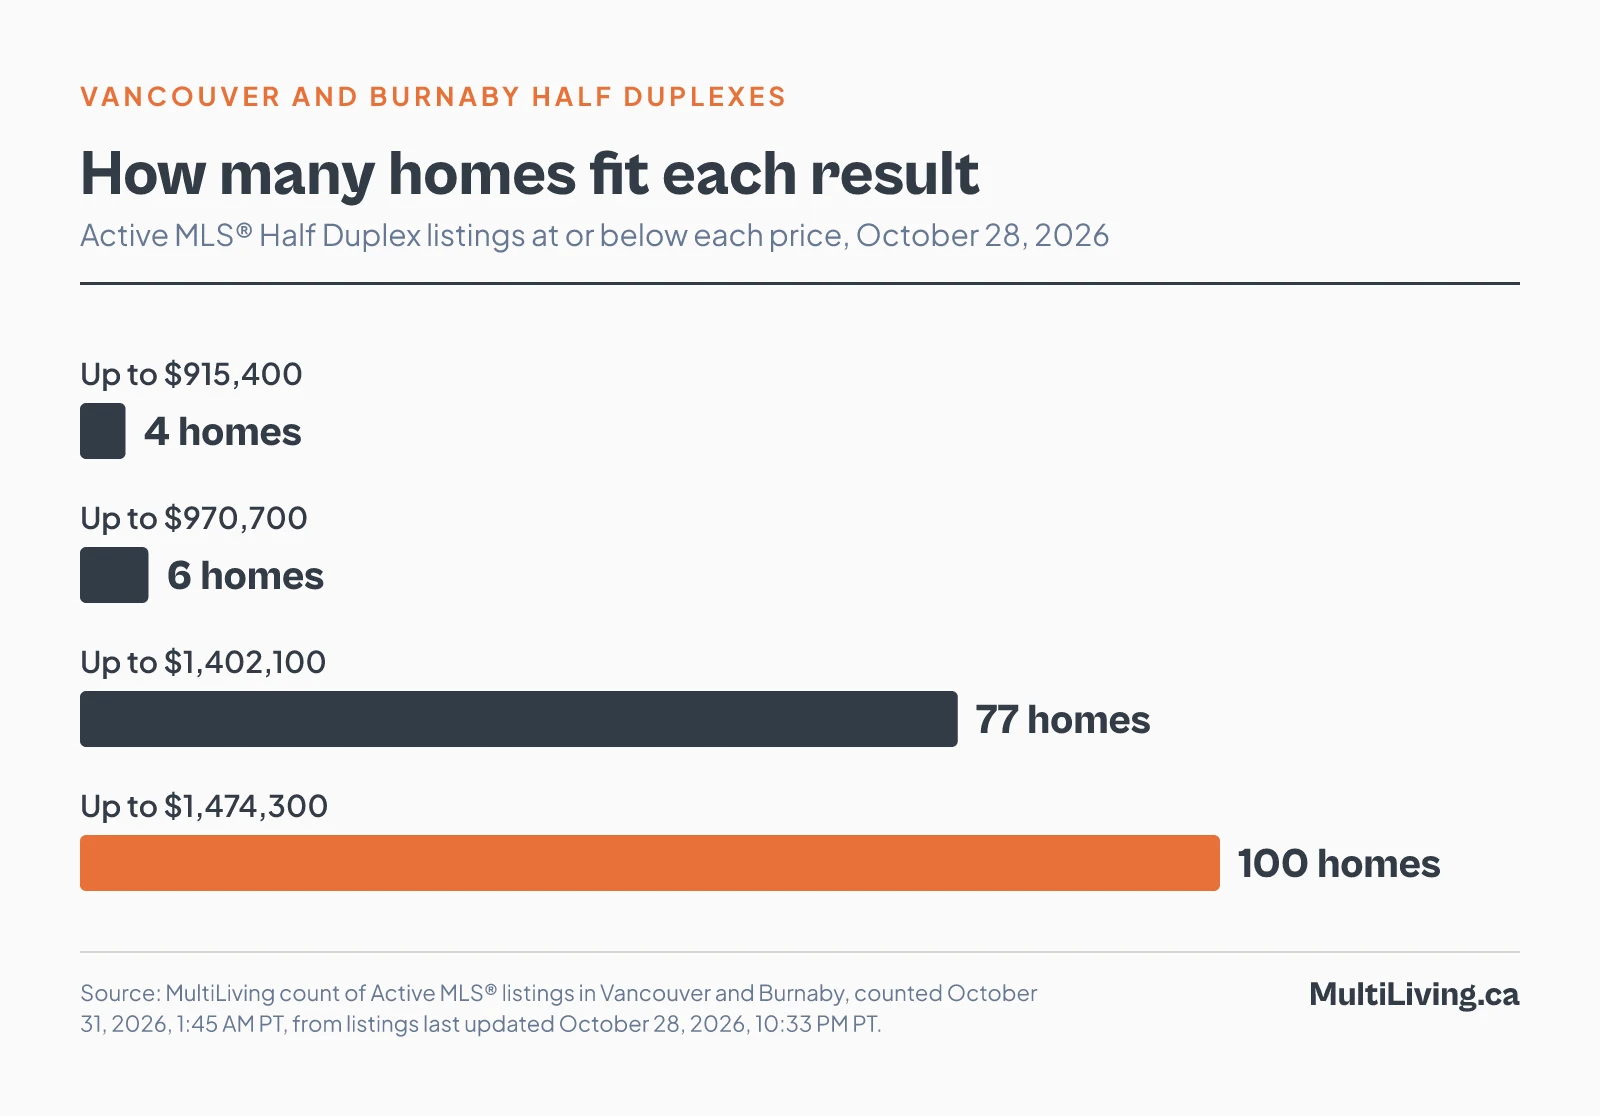
On October 28, 2026, our copy of the MLS® listings, which holds homes built in 2025 or later, had 361 Active listings filed as "Half Duplex" in Vancouver and 62 in Burnaby. At or below each result:
- $915,400: 4 homes, all in East Vancouver, 2 with 3 bedrooms and 2 with 2.
- $970,700: 6 homes, all in East Vancouver, 4 with 3 bedrooms and 2 with 2.
- $1,402,100: 77 homes, 73 in Vancouver and 4 in Burnaby.
- $1,474,300: 100 homes, 90 in Vancouver and 10 in Burnaby. 6 have 2 bedrooms, 77 have 3 and 17 have 4 or more.
All 100 give 2025, 2026 or 2027 as the year built. Two list a strata fee above the $350 the page assumes. 90 show $0 or no fee, so ask the seller for the strata budget. Our home search filters by price and bedrooms.
What a calculator cannot know
- The home's own strata fee and tax. The page uses $350 and 0.3 percent for every home.
- GST on a new home. It is 5 percent in BC, the Canada Revenue Agency says. A first-time buyer can get back up to $50,000 at or below $1 million, and a smaller amount up to $1.5 million. Ask whether the price includes GST.
- Whether you qualify for a transfer tax exemption. BC's newly built home exemption removes the tax up to $1,100,000, and part of it up to $1,150,000, for a buyer who qualifies. The page assumes you do while the box is ticked.
- Closing costs such as lawyer fees, an inspection and moving.
- Rent from a suite, which a lender may count. See which lenders count suite rent.
For a full budget, see our couple earning $200,000 with $150,000 saved.
Questions buyers ask
Is the calculator's price a pre-approval?
No. For a pre-approval, a lender asks for your papers and likely runs a credit check, the Financial Consumer Agency of Canada says.
Can I enter my exact rate?
Yes. The rate moves in steps of 0.01 percent, so 4.12 and 4.58 can be entered.
Does it work for Burnaby?
Yes. CMHC's limits apply across Canada. The page uses 0.3 percent tax everywhere.
Next step
Talk to our team to test a listing against your numbers.
General information only. These figures are examples from our calculator, using rules and rates in force on October 31, 2026. They are not financial or mortgage advice. Speak to a licensed mortgage broker before you make an offer.
Sources
- CMHC, "Purchase" (homeowner mortgage loan insurance), no date shown, read October 31, 2026.
- CMHC, "CMHC Home Start", no date shown, read October 31, 2026.
- Bank of Canada, "Interest rates charged for new and existing lending by chartered banks", residential mortgages, insured and uninsured, fixed 5 years and over, funds advanced, August 2026, read October 31, 2026.
- OSFI, "Minimum qualifying rate for uninsured mortgages", modified January 29, 2026, read October 31, 2026.
- Financial Consumer Agency of Canada, "Mortgage Qualifier Tool", modified March 1, 2019, read October 31, 2026.
- Financial Consumer Agency of Canada, "How much you need for a down payment", modified October 15, 2025, read October 31, 2026.
- Financial Consumer Agency of Canada, "Getting preapproved for a mortgage", modified October 15, 2025, read October 31, 2026.
- Canada Revenue Agency, GST/HST calculator and rates by province, modified October 7, 2026, read October 31, 2026.
- Canada Revenue Agency, first-time home buyers' GST/HST rebate, "What is the rebate", modified March 30, 2026, read October 31, 2026.
- Province of BC, newly built home exemption, last updated January 6, 2026, read October 31, 2026.
- MultiLiving calculator at /affordability, code of October 31, 2026, run for each example with no other debts. The calculator rounds prices down to the nearest $100; payments are our calculation from its code.
- MultiLiving count of Active MLS® listings in Vancouver and Burnaby filed as "Half Duplex", using the price, bedrooms, strata fee, year built and MLS® area of each record. Counted October 31, 2026, 1:45 AM PT, from listings last updated October 28, 2026, 10:33 PM PT. Our copy of the MLS® listings holds homes built in 2025 or later.
Related Resources
Multiplex for Sale in Vancouver
Browse all Vancouver listings
Where to Buy in Vancouver
Neighbourhood comparison guide
Vancouver Pre-Sales
Active & upcoming projects
Multiplex for Sale in Burnaby
Browse all Burnaby listings
Where to Buy in Burnaby
Neighbourhood comparison guide
Burnaby Pre-Sales
Active & upcoming projects